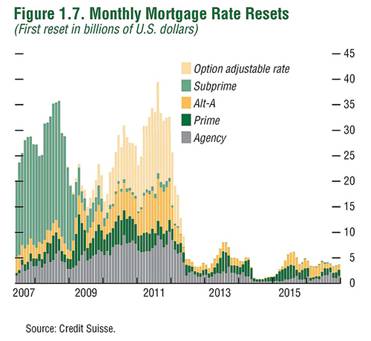
The conclusions, more or less, are that while the first wave of mortgage defaults in the "Subprime" category has
Since this crisis began, the profile of mortgage resets has been well-correlated with subsequent foreclosures. . . .
As the recent housing bubble progressed, the profile of mortgage originations changed, so that at the very peak of the housing bubble, new originations took the form of Alt-As (low or no requirement to document income) and Option-ARMs (teaser rates, with no required principal repayments).A broader profile of mortgage resets is presented below (though even this chart does not include the full range of adjustable mortgage products).
This reset profile is of great concern, because the majority of resets are still ahead. Moreover, the mortgages to which these resets will apply are primarily those originated late in the housing bubble, at the highest prices, and therefore having the largest probable loss.

 Posts
All Comments